A simple timeline
Every purchase moves at its own pace, but this order works for most buyers.
- Offer accepted: request quotes and share the home's details.
- After the inspection: review what you learned, like roof age, and choose coverage.
- One to two weeks before closing: bind the policy and send proof to your lender.
- Closing: your first year's premium is paid, and your escrow account may be funded.
Why starting early helps
Most homes are easy to insure. Some aren't. An older roof, a home in a flood zone, past claims on the property or a location near the coast can limit which carriers will write a policy, or change the price. Finding that out a week before closing leaves little room to compare.
Your inspection report can help. Carriers often ask about the roof, electrical, plumbing and heating systems.
What your lender needs
Lenders require the home to be insured before they fund the loan. They'll typically ask for a declarations page, sometimes called a dec page, or an insurance binder. It should show:
- The property address and coverage start date.
- Your dwelling coverage amount.
- Your deductible.
- The lender listed as mortgagee, with its loan number and address.
- The premium, and whether it has been paid.
How the first year is paid
If you're buying a home with a CapCenter mortgage, you'll pay at least your first year's homeowners insurance premium. Many buyers pay it at closing as part of their cash to close. It's standard for a loan to have an escrow account for future taxes and insurance, so you may also fund an escrow account at closing. Those aren't closing costs. They're payments you'd owe either way, so CapCenter's ZERO Closing Costs offer doesn't cover them.
Flood insurance is separate
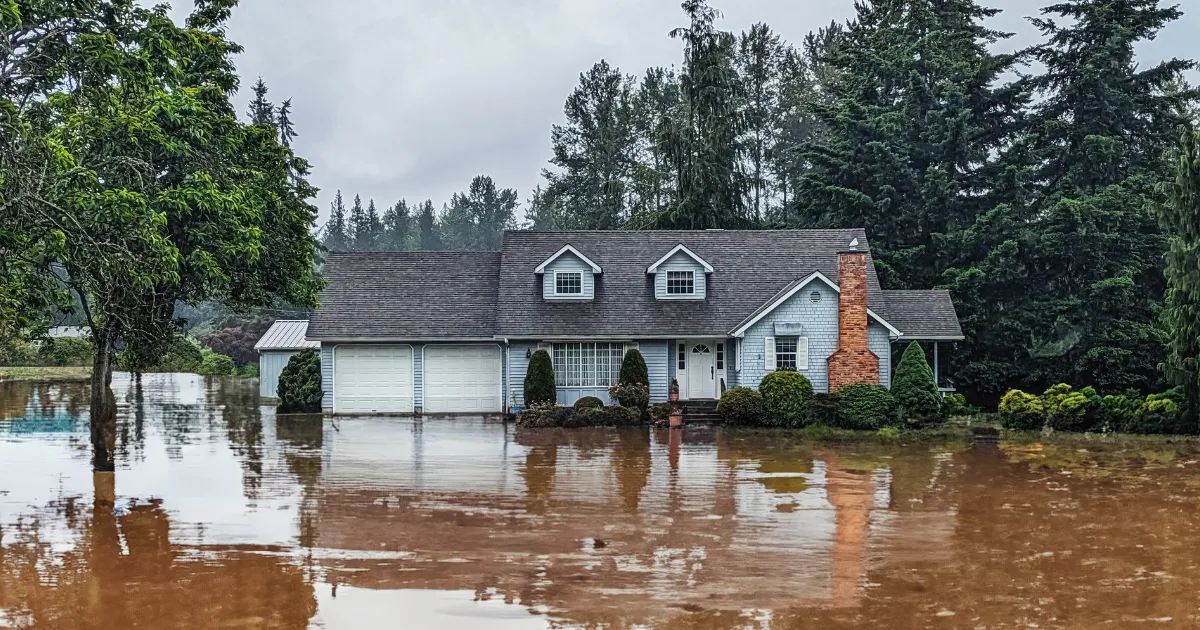
Standard homeowners policies don't cover flood. If the home is in a high-risk flood zone and you have a federally backed mortgage, your lender will require flood insurance. Ask about the flood zone early, because a flood policy can have its own waiting period and cost.
How CapCenter's insurance agency helps
Our in-house agency compares coverage across multiple carriers. If you're financing with CapCenter, our insurance team works next to your loan consultant, so your policy and proof of insurance can be sent straight to closing. You don't need a CapCenter mortgage to get a quote.