 Home & auto, one team
Add auto to your home policy.
We compare 20 carriers. Clients save 20% on average. Believe It.
- Tell us what to cover (about 3 min)
- Your agent compares 20 carriers
- You get your options the same business day
Including Travelers, Progressive, Safeco and Utica National.
One agency, one renewal date.
Already insuring your home with us, or about to? Adding your cars is the easy win.
Multi-policy discount
Bundling home or renters with auto usually earns a multi-policy discount.
One agency
Home & auto with our in-house agency. One team to call when something happens.
One renewal date
One date for home & auto, and we re-shop at renewal if your rate goes up.
Limits that line up
An umbrella needs set liability limits on both policies. Quoting them together means they match from day one.
Your limits, in plain English.
Auto limits come as three numbers, like 100/300/100. Here's what each one pays for, plus the rest of the policy.
Pays for injuries you cause to other people. Two numbers: the most per person, and the most for everyone in one accident.
First two numbersPays for what you damage: the other car, a fence, a storefront. Newer cars cost a lot to repair.
Third numberPays for your injuries when the other driver has no insurance, or not enough. Required in every state below.
Protects youRepairs your car after an accident, whoever's at fault, minus your deductible. Lenders and leasing companies usually require it.
Your carTheft, weather, fire, falling trees & animals. The deer on a back road is a comprehensive claim.
Your carMedical bills for you & your passengers, regardless of fault. Maryland also requires $2,500 of personal injury protection (PIP).6
You & passengersYour state's legal minimum
In thousands of dollars.
Virginia: For policies effective on or after January 1, 2025.
- Uninsured/underinsured motorist coverage must be included. It matches your liability limits unless you reject the higher amount, and can't go below the minimum.
| State | Person | Accident | Property |
|---|---|---|---|
| VA1 | $50,000 | $100,000 | $25,000 |
| MD5 | $30,000 | $60,000 | $15,000 |
| NC7 | $50,000 | $100,000 | $50,000 |
| DC8 | $25,000 | $50,000 | $10,000 |
Bodily injury per person and per accident, and property damage: the liability minimums for private passenger vehicles. We also insure clients in other states; your agent will confirm the rules where you live.
Why minimums fall short
Made-up exampleSay you rear-end a newer SUV at a light, and two people in it are hurt. Here's how the bills might land, with your state's minimum versus higher limits.
With Virginia's minimum limits, the policy stops paying at its limits and the rest can come back to you, including your savings.
Illustrative only. The costs are invented to show how limits work, not typical claim amounts. Real claims depend on the facts, your policy and the law.
Do you need an umbrella?
An umbrella is extra liability coverage above your home & auto limits. If a serious claim uses up the liability on your car or home policy, the umbrella picks up from there.
Worth a look if:
- Your home equity and savings are more than your liability limits
- You have a teen driver, or several drivers in the house
- You own a rental property
- You have a pool, a trampoline or a dog that's known the mail carrier a little too well
Your auto and home liability pay first. The umbrella sits on top of both.
Grab these & you’re done in 3 minutes.
The form takes about 3 minutes. The first list is what it asks. The second is what your agent will need when you talk, to price every driver and car.
Just auto?
No problem. Plenty of clients start with their car. We'll quote auto on its own and compare it across carriers the same way.
Get an auto quoteReal people, not a call center.
As a local provider, we're easy to talk to. We don't operate a call center, so you'll have a dedicated, licensed representative.
- Next to your loan officerOur insurance team works next to your loan officer, so your policy is ready on time.
- Not on commissionSalaried agents compare carriers for you.
- Every yearWe re-shop at renewal if your rate goes up.
- Same teamMortgage, insurance & settlement under one roof.
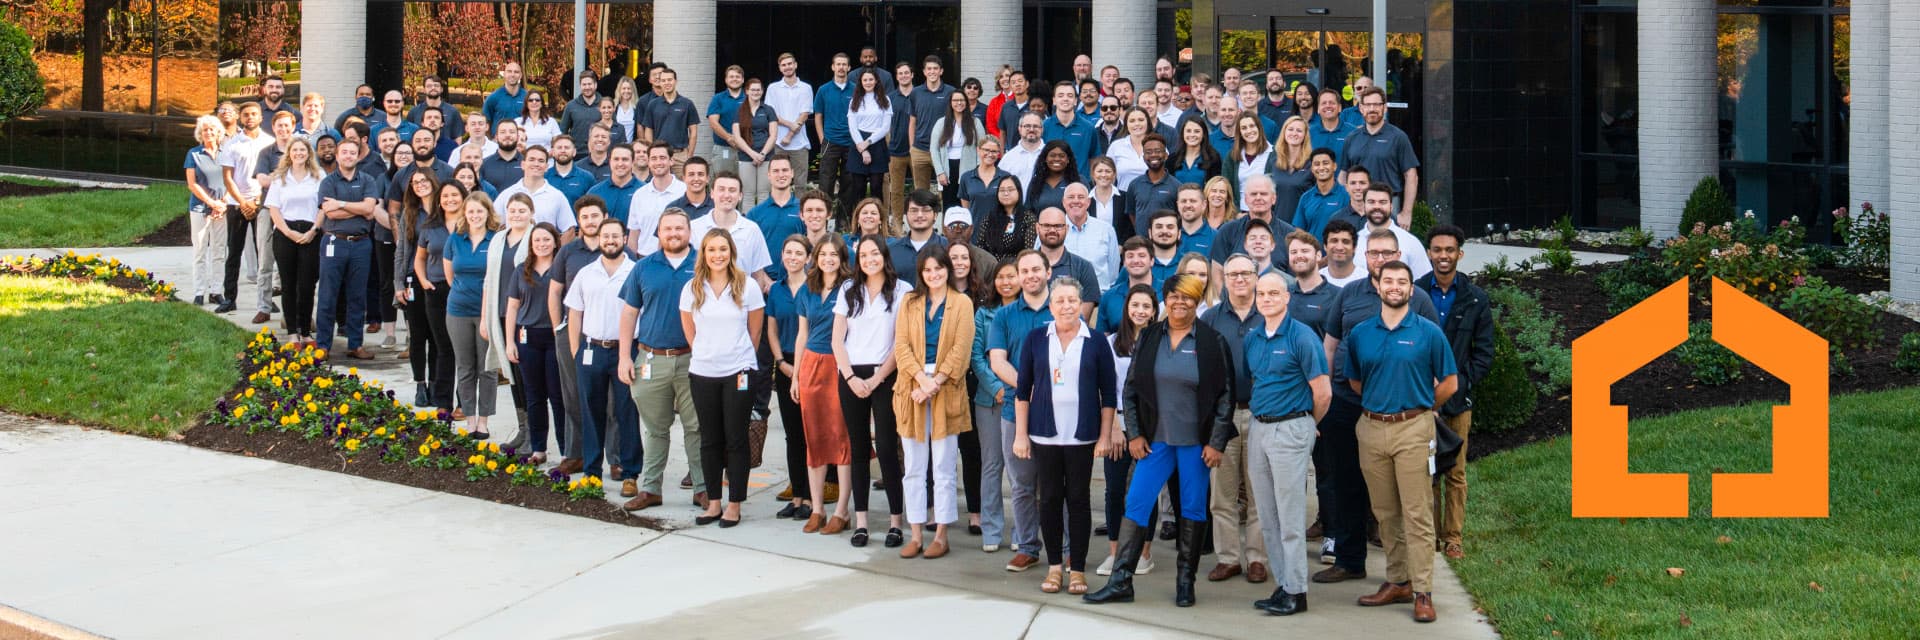 Family owned since 1997
Need help with a policy or a claim?
Filing a claim?
For a claim, your carrier's claims line, usually open 24/7, is on your policy's declarations page or ID card.
Good questions, straight answers.
Can I bundle auto with my home insurance?
Yes. Choose Home & Auto on the quote form and we'll quote them together. Bundling home or renters with auto usually earns a multi-policy discount, plus one agency and one renewal date.
What does 50/100/25 mean?
Those are liability limits in thousands of dollars: up to $50,000 for each person you injure, $100,000 for everyone injured in one accident, and $25,000 for property you damage. Those happen to be Virginia's minimums for policies effective on or after January 1, 2025.2
Is my state's minimum coverage enough?
It's enough to drive legally. It's often not enough to cover a serious accident, and anything above your limits can come back to you. Virginia's Bureau of Insurance advises buying more than the minimum. We'll show you options at a few limit levels so you can see the price difference.4
What's uninsured / underinsured motorist coverage?
Do I need collision and comprehensive?
State minimums don't include them. If your car is financed or leased, your lender or leasing company usually requires both. On an older car you own outright, it can make sense to weigh the premium against what the car is worth. We'll price it both ways.
How is an umbrella different from my auto liability?
Your auto liability pays first, up to its limits. An umbrella adds liability coverage on top of your home and auto policies. Carriers require minimum limits on both underlying policies, so we quote them together.
Do I need a CapCenter mortgage to get an auto quote?
No. Anyone can get a quote, for auto alone or for home & auto together.
What if my rate goes up at renewal?
We re-shop at renewal if your rate goes up. Salaried agents compare carriers for you.
Compare auto insurance rates.
- Tell us what to cover (about 3 min)
- Your agent compares 20 carriers
- You get your options the same business day
- Virginia Department of Motor Vehicles: Insurance Requirements ($50,000 / $100,000 / $25,000 for policies effective on or after January 1, 2025).
- Code of Virginia: § 46.2-472 (minimum limits; effective date January 1, 2025).
- Code of Virginia: § 38.2-2206 (uninsured motorist coverage; equals liability limits unless a named insured rejects the additional coverage).
- Virginia State Corporation Commission, Bureau of Insurance: Virginia Auto Insurance Guide ("You should buy more than the minimum limits required by law.").
- Maryland Motor Vehicle Administration: Auto Insurance Requirements in Maryland ($30,000 / $60,000 / $15,000).
- Maryland Insurance Administration: Consumer Advisory: Will I need to pay a penalty if I do not have automobile insurance? (matching uninsured/underinsured bodily injury; $15,000 uninsured property damage; $2,500 PIP).
- North Carolina DMV: Vehicle Insurance Requirements ($50,000 / $100,000 / $50,000 for policies issued or renewed after July 1, 2025; uninsured/underinsured coverage required).
- District of Columbia DMV: Vehicle Insurance ($25,000 / $50,000 / $10,000; uninsured motorist $25,000 / $50,000 bodily injury and $5,000 property damage with a $200 deductible).
Coverage descriptions are general and for education only. Your policy's terms, conditions and exclusions govern, and coverage varies by carrier and state. State minimums checked October 2026; laws change, so confirm with your agent.
Restrictions apply. See CapCenter.com for details. NMLS ID #67717, nmlsconsumeraccess.org